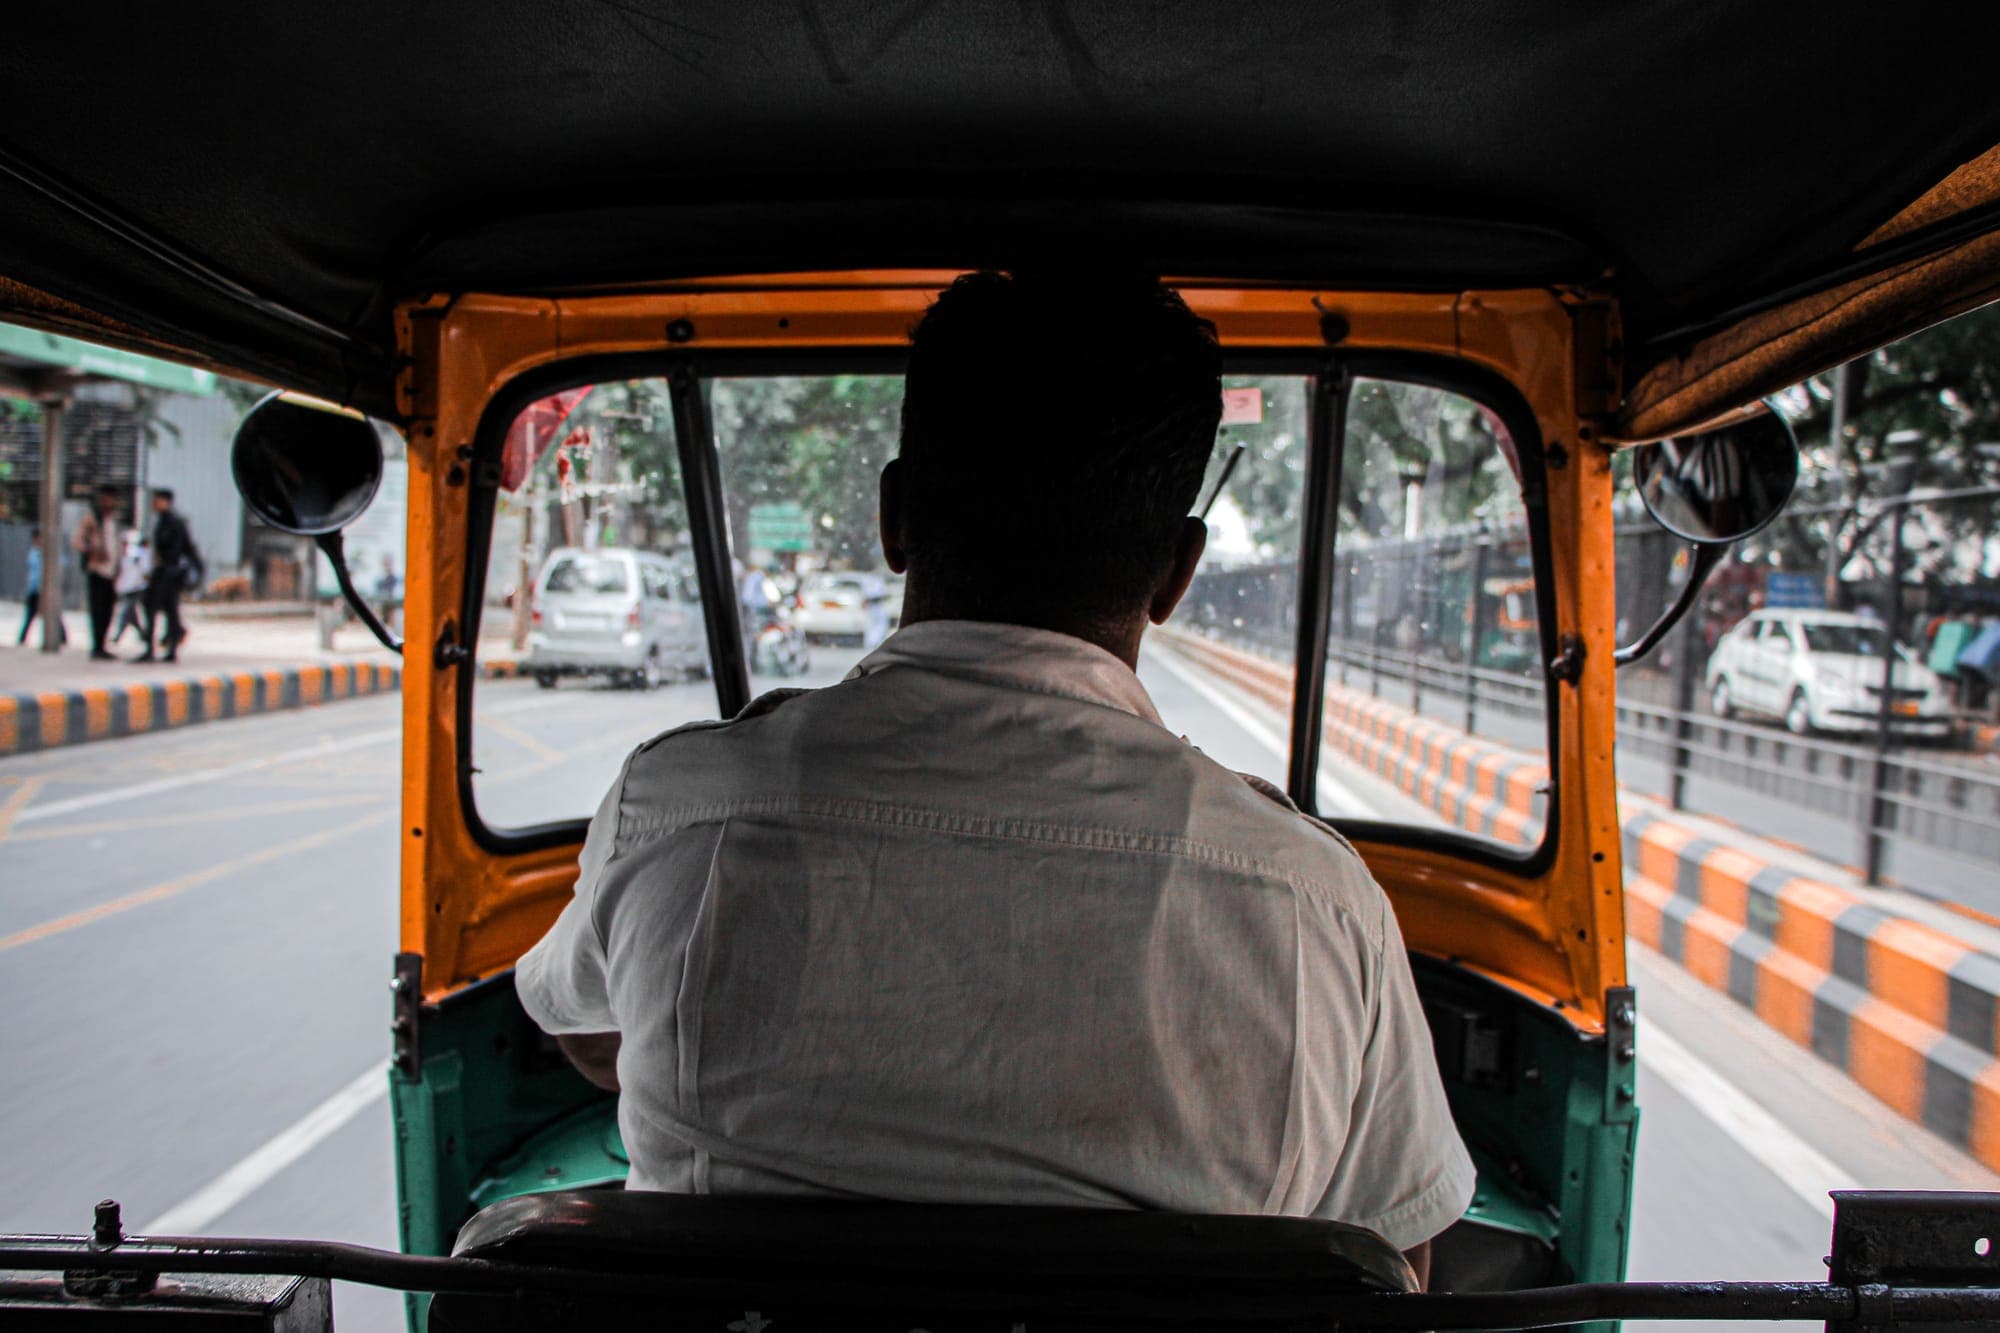
The Delivery Rider Who Got Paid Without Filing a Claim: Index-Based Insurance and the Gig Economy
India's gig workforce stood at 7.7 million workers in 2020-21 and is expected to reach 23.5 million by 2029-30. Delivery riders, cab drivers, and platform-based workers earn only when they work.
A flooded road or a heatwave advisory does not come with paid leave. There is no separate HR department or sick pay for them. Every stopped shift is a direct income cut. For millions of workers, extreme weather is not just a safety challenge but an immediate financial shock.
A single day without work can mean delayed bills, borrowed money, or reduced household spending.
India's gig economy is growing rapidly, but extreme weather can erase a rider's income overnight. Index-based insurance offers faster, automated financial protection.
Written byAnkur IndrakushFounder & CPTO
What Extreme Weather Actually Costs a Gig Worker
Traditional insurance does not fit the gig worker's situation well. Most policies require proof of loss, a claims assessor, and a waiting period. That structure was built for salaried employees with fixed assets and predictable income records.
A delivery rider losing two days of income during a monsoon downpour has no property to assess. The loss is invisible to a standard insurance system. No surveyor can visit and verify that the roads were flooded, that orders dried up, or that the rider chose safety over income.
The financial reality for most gig workers is stark:
- No employer-funded accident or weather cover
- No paid rest entitlement during extreme weather
- Income losses that compound across multiple bad weather days in the same month
- Informal debts taken to cover gaps between weather events and recovery
India's 2025 monsoon delivered 108% of the long-period average rainfall nationally, but with severe spatial unevenness. Parts of north and northeast India faced 20% below-normal rainfall, meaning drought, not floods, while other zones were inundated. For a rider in Patna or Guwahati, the season could mean days of waterlogged streets and zero deliveries.
What Index-Based Insurance Is and Why It Fits Gig Work
Index-based insurance, also called parametric insurance, pays out when a publicly verifiable number crosses a pre-set threshold. That number is called the index. It could be daily rainfall at a city weather station, or temperature for a defined number of consecutive hours.
No loss assessment is needed or separate claim form is filed. The weather data decides, which makes automated insurance claims processing possible at a scale and speed that traditional insurance cannot match for informal workers.
Think of it this way. A delivery rider buys a weather-linked income protection product before the monsoon. The product states that if cumulative rainfall at the nearest IMD station exceeds 80mm in a single day, a fixed payout of ₹300 is transferred to the rider's bank account. That's gig worker climate insurance, which is structured around verifiable data, not individual proof of loss.
What Changes When a Gig Worker Has This Cover
The difference with gig worker climate insurance is not just financial. It is structural.
Without index-based insurance, a gig worker facing a bad monsoon week faces an immediate choice: ride in dangerous conditions or lose income. With cover, a bad-weather payout provides a third option: stop, stay safe, and receive a replacement income that week.
The outcomes shift in three concrete ways:
- Speed: A payout triggered by verified IMD data offers seamless claims settlement and can arrive in days. There is no queue, no assessor visit, and no documentation burden.
- Certainty: The payout amount is known in advance. A rider can plan around it the same way a salaried worker plans around paid leave.
- Dignity: The claim process does not require a worker to prove hardship to an authority. The weather station does the verification.
Heatwave and Rainfall Events Affecting Gig Workers: India 2025
| City / Region | Event Type | Impact Period | Gig Worker Risk |
|---|---|---|---|
| Rajasthan, Haryana | Heatwave (45°C+) | June 2025 | Outdoor work advisory issued |
| North and Northeast India | 20% rainfall deficit | June–August 2025 | Low delivery demand; drought stress |
| Punjab | Severe monsoon flood | August 2025 | 1,400+ villages affected; roads impassable |
| Patna, Bihar | Exceptional drought, then floods | July–August 2025 | Erratic conditions; income disruption |
| Ahmedabad | Heatwave (43.6°C+) | Summer 2025 | Income lost due to extreme heat days |
Where Index-Based Insurance Has Limits
Index-based cover is not a complete solution. Every gig worker considering it should understand two specific gaps.
Basis Risk for Triggers Set
The trigger relies on a weather station reading, not your personal experience. A rider in a low-lying Chennai neighbourhood could face severe waterlogging while the nearest IMD station records moderate rainfall. The rainfall limit is not triggered; as a result, no payout arrives despite real income loss.
This is known as basis risk, and it is one of the most important considerations when evaluating any parametric insurance product.
Payout Promised Compared to Actual Losses
The payout amount is set in advance. If a rider loses ten days of income during a severe flood event but the product pays for three days, the shortfall is the rider's problem. Index cover provides partial protection, not full income replacement.
How to Manage the Associated Limits
Treat the payout from automated insurance claims processing as a financial buffer, not a complete replacement for lost income.
It is also important to choose products with triggers calibrated to the specific city or locality rather than relying on broad regional averages. Where available, gig workers and other informal workers can explore parametric products offered through IRDAI-registered insurers.
Wrapping Up
Gig workers are already absorbing the income cost of India's intensifying weather. Index-based insurance cannot fix the deeper policy gaps: no paid leave, no employer protection, and no minimum earnings guarantee.
But it can provide a predictable, fast payout when a weather event crosses a predefined threshold. India's Code on Social Security, 2020, recognises gig workers for the first time. As implementation expands, seamless claims settlement through weather-linked income cover is one of the more practical tools available for protecting informal workers from climate-driven income shocks.
Curious About Weather-Linked Income Cover?
Check whether index-based parametric insurance products are available for informal and gig workers in your city through IRDAI-registered general insurers. Compare the trigger, payout amount, geographic coverage, and basis-risk conditions before choosing a product.
00 Comments
Start the conversation
Be the first reader to share a thoughtful response.
Leave a Reply
Your email address will not be published. All comments are reviewed before appearing publicly.